- Invested amount
- Estimated returns
- Invested amount
- —
- Estimated returns
- —
- Total value
- —
- Value without step-up
- —
Figures are estimates for planning only, not investment or tax advice.
A step-up SIP raises your monthly instalment by a fixed percentage every year, usually to match a salary increase. This calculator shows how much that changes the outcome compared with a flat SIP.
Why it works so well
The extra money goes in early enough to compound, and it keeps the real value of your investing constant against inflation. A 10% annual step-up on a ₹5,000 SIP over 15 years typically produces a corpus 40–50% larger than the flat version, for a contribution that never feels like a stretch.
The formula
The calculation is done year by year: each year’s twelve instalments are compounded for the months remaining, then the instalment is raised by the step-up percentage for the following year. The result shows both the stepped-up total and what a flat SIP of the same starting amount would have produced.
Frequently asked questions
What step-up should I choose?
Match it to your expected annual increment — 5% to 10% for most salaried investors.
Do fund houses support step-up SIPs automatically?
Most do, under names like “SIP top-up”. You set the increase once and it applies each year.
Can I skip a step-up in a bad year?
Yes. Skipping one increase only affects the instalments from that year onwards.
Related calculators
See allRead next
Step-up SIPs: the ten-minute change that adds 40% to your corpus
Raising your instalment with your salary is the least painful way to invest meaningfully more.
Step-up SIPs: the ten-minute change that adds 40% to your corpus
Raising your instalment with your salary is the least painful way to invest meaningfully more.
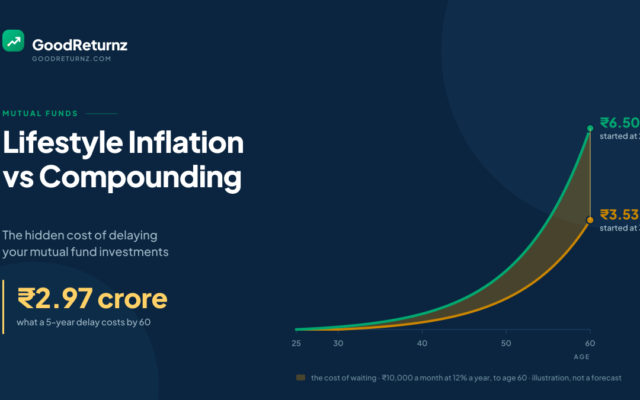
Lifestyle Inflation vs. Compounding: The Hidden Cost of Delaying Mutual Fund Investments
In this articleLifestyle inflation is invisible because it is proportionalWhat a delay actually costsWhy the first years are the expensive…